A Shipper’s Guide to Navigating Freight Insurance and Liability
Blog Post CTA
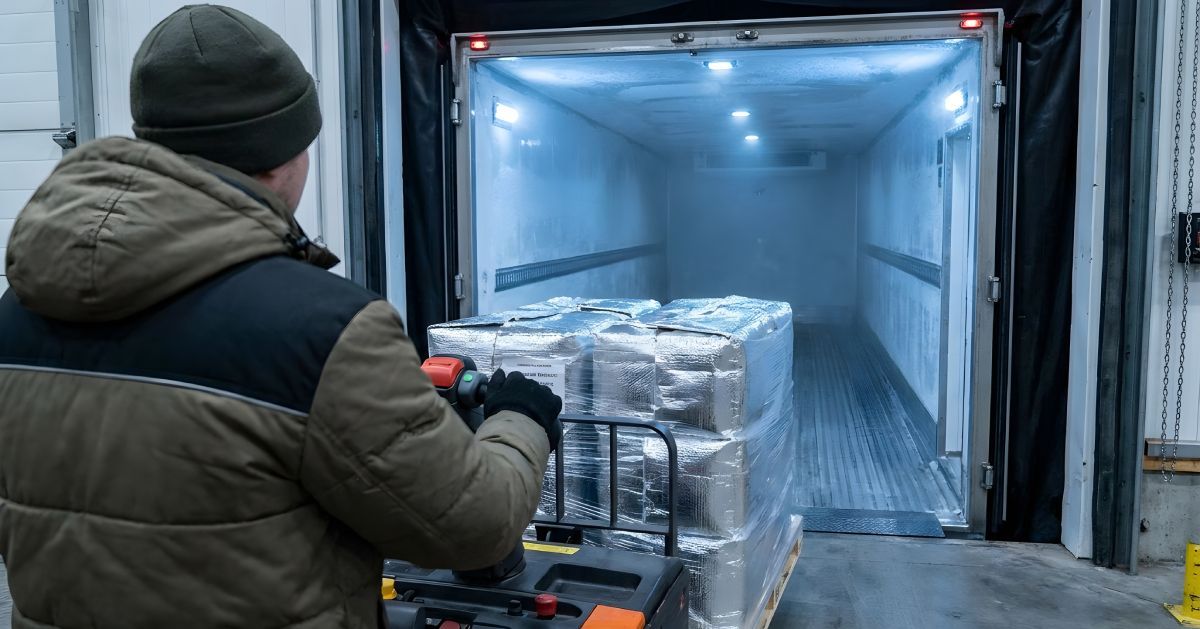
While freight insurance and liability are topics that shippers do not enjoy working through, anyone moving freight would want to be secure when an exception event lands on their desk. Say a reefer unit fails somewhere on I-40 and a load of frozen shrimp shows up at 41°F. Inevitably, the receiver rejects it, then you file a claim, wait three months, and get back a check for a fraction of what the load was worth.
Unfortunately, that is not uncommon, but you can avoid much of it. You just need to know the difference between freight insurance and liability, who pays, how much, and what reduces a claim.
Carrier Liability vs. Freight Insurance: Not the Same Thing
Carrier liability and freight insurance aren’t the same, but people mix them up. Under the Carmack Amendment, a carrier that hauls your goods across state lines is liable for loss or damage in transit. In principle, that means the full actual value of the freight. But while liability is a legal duty, insurance is how the carrier pays for that duty, and the two numbers often don’t match.
In many cases, the cargo limit you get is whatever the carrier chose to buy or whatever you demanded. For example, if a carrier has a $100,000 cargo policy and is hauling $180,000 worth of beef, you can see where the gap comes from. If it is a small company, you may never see the balance even if, on paper, the carrier owes you.
What Shrinks a Freight Claim
These factors are important to note because they affect what you get in the event of a crash or some other situation:
Released Rates
LTL carriers often cap what they’ll pay at a set amount per pound. If you don’t declare a higher value on the bill of lading, a pallet of specialty cheese may pay out by weight instead of by invoice. But declaring value costs extra.
Policy Exclusions
Cargo policies can leave out unattended trucks, certain goods, or reefer breakdown. That last one stings because if the reefer unit fails and the policy excludes mechanical breakdown, the insurer may refuse to pay, even though the carrier is still liable under the law.
Filing Deadlines
You usually have nine months from delivery to file a written claim. The carrier then has 30 days to acknowledge it and 120 days to pay, decline, or make you an offer, though in practice some carriers drag that out with requests for more documents. Your contract or the bill of lading can change some of these terms. Read them before you need them, because filing a strong claim in month 10 may get you nothing.
Where Brokers Fit in the Picture
Before now, brokers weren’t liable for cargo the way a carrier is, and most shippers don’t think about that until a claim lands on the broker’s desk and gets passed straight to the carrier. Some carry contingent cargo coverage, which may pay if the carrier’s policy fails. But terms vary widely from broker to broker, so don’t count on it without seeing the policy.
One thing did change this year. In May 2026, the Supreme Court ruled in
Montgomery v. Caribe Transport that brokers can face state claims for hiring unsafe carriers. That case involved a highway injury, not lost freight, and it’s too early to say how it will play out. However, it will likely push brokers toward tighter carrier checks, which would benefit shippers in the long term.
Should You Buy Your Own Cargo Coverage?
Shipper’s interest coverage, which is sometimes sold as all-risk, pays you first. Your insurer then goes after the carrier, which means you aren’t the one waiting four months for a check. The coverage costs money, but think about a distributor running 30 reefer loads a week of fresh produce, and one rejected load could top $60,000.
For that shipper, a year of premiums may cost less than a single bad week. For someone moving low-value dry goods on short lanes, the math probably doesn’t work. Run it on your own lanes.
A Pre-Shipment Checklist for Shippers
Before a load moves:
- Ask about reefer breakdown.
- Put the nine-month deadline on someone’s calendar.
- Declare value when the released rate won’t cover you.
- Keep temperature logs, photos, and signed delivery receipts, since claims are often won or lost on paperwork.
- Get a current certificate of insurance from the carrier and check the cargo limit against your highest-value shipments.
How EFS Reduces Freight Risk
Entourage Freight Solutions checks carriers before they touch your freight. With more than 4,500 dry freight carriers and 3,500 prequalified reefer carriers, there’s room to match each load with a carrier whose coverage fits it. Cradle-to-grave tracking gives you a clear record of every shipment. IoT-enabled temperature monitoring flags problems while the truck is still moving, so the team can act before the product is lost. And 24/7 operations staffing means a 2 a.m. problem gets handled at 2 a.m.
If you want a second look at how your freight is covered,
contact us today to get started.